
PDD Holdings 2025 Q4 Earnings: Growth Significantly Slows, Full Bet on Supply Chain Investment to Build the "New Pinduoduo"
 Bitget2026/03/25 13:02
Core Highlights
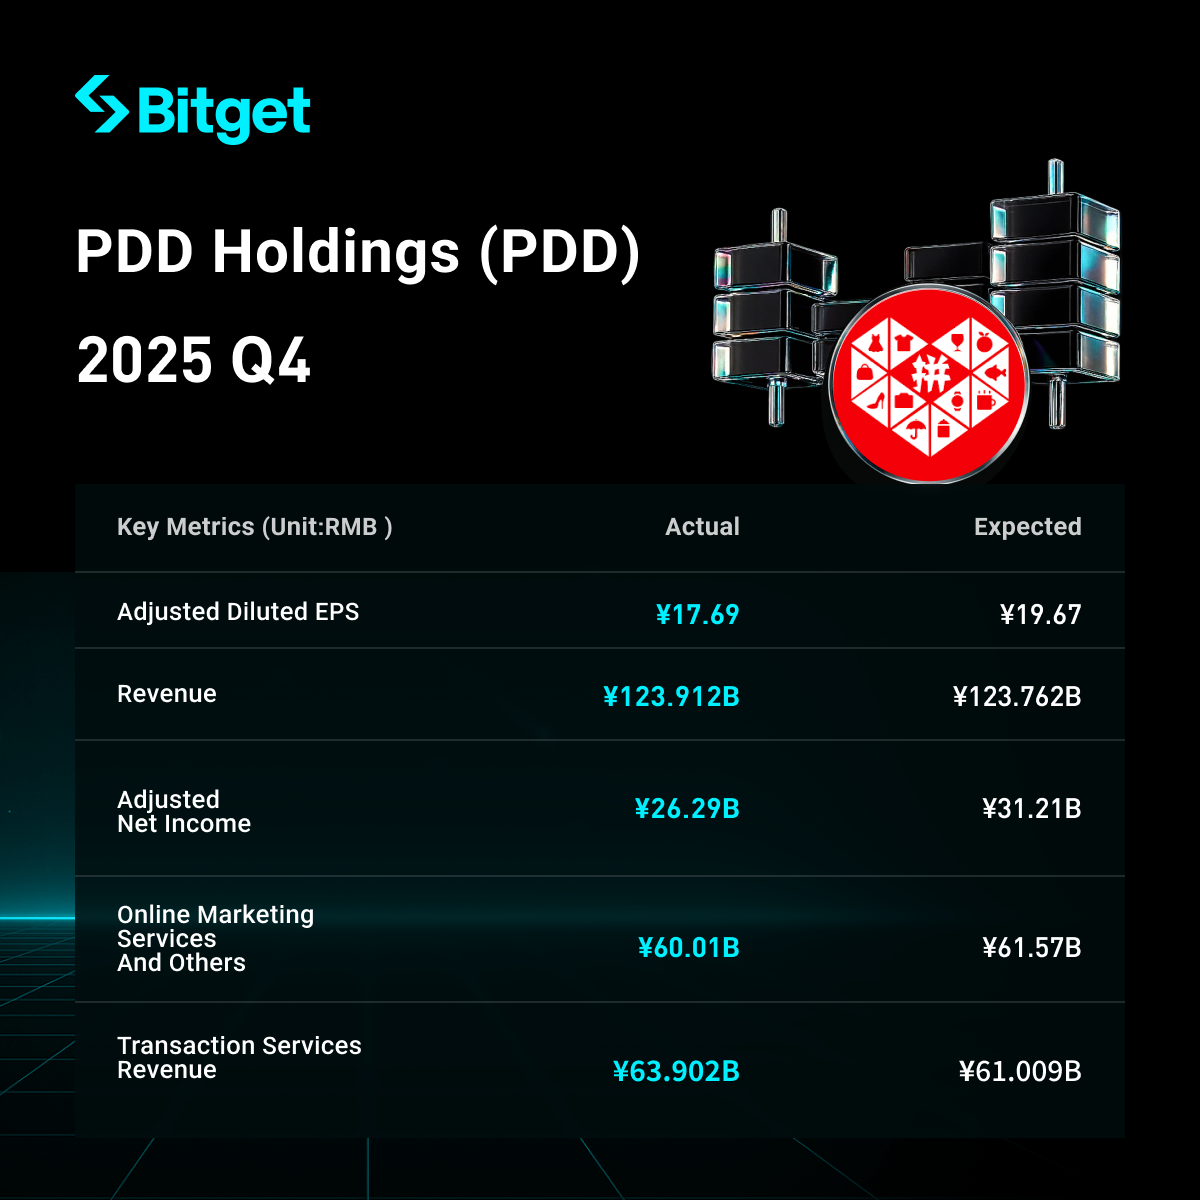
PDD Holdings (PDD) delivered steady revenue growth in Q4 2025, but net profit declined year-over-year and fell short of market expectations. Total revenue slightly exceeded analysts’ forecasts, primarily driven by strong transaction services performance, while profit pressure stemmed from continued investments in supply chain and ecosystem development. Operating cash flow decreased, yet cash reserves rose significantly. The company announced a RMB 100 billion investment over the next three years for supply chain infrastructure and officially established “New Pinduoduo” to advance self-owned brands and global supply chain integration. The stock reacted positively, rising approximately 1.91% on the day. Overall, short-term results faced pressure, but the long-term strategy focuses on supply chain upgrading.
Detailed Breakdown
- Overall Revenue and Profit Performance
- Total revenue: RMB 123.912 billion (approx. USD 17.719 billion), up 12% YoY from RMB 110.610 billion in the prior-year period, slightly above market consensus of RMB 123.762 billion.
- Operating profit: RMB 27.720 billion, up more than 8% YoY from approx. RMB 25.592 billion.
- Net income attributable to ordinary shareholders: RMB 24.541 billion, down 11% YoY from RMB 27.446 billion.
- Non-GAAP net income attributable to ordinary shareholders: RMB 26.295 billion, down 12% YoY and missing consensus estimate of RMB 31.210 billion.
- Earnings per share (EPS): Basic EPS RMB 17.50 (prior-year RMB 19.76); diluted EPS RMB 16.51 (prior-year RMB 18.53); adjusted diluted EPS RMB 17.69 (prior-year RMB 20.15).
- Net cash from operating activities: RMB 241.195 billion (prior-year RMB 295.472 billion).
- Cash and cash equivalents plus short-term investments: RMB 422.3 billion (approx. USD 60.4 billion) at year-end, significantly higher than RMB 331.6 billion at the end of the previous year.
- Core Business Performance
- Online marketing services and other revenues: RMB 60.010 billion (approx. USD 8.581 billion), up 5% YoY.
- Transaction services revenue: RMB 63.902 billion (approx. USD 9.138 billion), up 19% YoY — the primary driver of overall revenue growth.
- Other Business Segment Performance (The report does not provide further breakdown of individual segments such as international business Temu. Revenue is mainly presented in two categories: online marketing services and transaction services. Overall growth was led by transaction services, while slower growth in marketing services may reflect intensified competition.)
- Future Plans: Supply Chain Investment and “New Pinduoduo” Establishment
- The company is fully committed to supply chain development and has officially formed “New Pinduoduo” to integrate supply chain resources across Pinduoduo and Temu, incubate self-owned brands, and target the global market.
- A new special-purpose company was established in Shanghai with an initial cash injection of RMB 15 billion.
- Planned total investment over the next three years: RMB 100 billion, aimed at systematically operating brands across different markets and categories, and upgrading “Made in China” to higher value chains.
- CEO Chen Lei emphasized adherence to long-termism and greater resource commitment to stakeholders; Co-CEO Zhao Jiashun noted that 2026 marks the start of the next decade and supply chain investment is a core commitment; CFO Liu Jun pointed out that continued exploration and investment amid changing external conditions will impact short-term financial performance.
- Next Quarter Guidance (No specific revenue or operating income guidance for Q1 2026 or the full year was disclosed. The company stressed that future results may fluctuate due to ongoing investments and that the current quarter’s profit should not be viewed as indicative of future performance.)
- Market Background and Investor Concerns
- Core Tension: Steady revenue growth (driven by transaction services) versus declining profit (due to increased investments). Non-GAAP net profit declined both year-over-year and significantly missed expectations, reflecting higher spending on supply chain, R&D, and ecosystem support.
- Market Challenges: Rapidly evolving competitive landscape, changing consumer demand, and global regulatory pressures.
- Investor Reaction: Despite the profit miss, revenue slightly beat expectations and the announcement of a massive supply chain investment plan elicited a positive market response, with PDD shares rising 1.91% on the day. Investors are mainly concerned about short-term profitability being pressured by investments, but acknowledge the long-term strategic value of supply chain upgrading.
Disclaimer: This article is for reference only and does not constitute any investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Chipmaker earnings growth cools to 136% as AI boom lifts S&P 500
Updated: Delta Air Lines warns that as fuel prices hit profits, airline capacity will tighten further
Delta Airlines lowers its annual profit forecast due to an expected increase in fuel costs to $6 billion. The CEO stated that ticket prices have risen by about 20% this year, with limited passenger resistance. Analysts warn that maintaining high ticket prices in 2027 is critical for improving profitability. The article includes comments from the earnings call and analyst remarks. Rajesh Kumar Singh/Shivansh Tiwary, Reuters Chicago, October 9 - Delta Airlines (DAL.N) said on Friday that, despite strong travel demand and rising ticket prices, soaring fuel costs have forced it to cut its 2026 profit expectations by nearly a quarter. So, the airline industry may need to further limit flight growth next year to protect profitability. This warning highlights the increasingly tough challenges faced by U.S. airlines. While strong demand and restricted seat growth have allowed airlines to significantly raise ticket prices and offset higher fuel costs, aggressively increasing flights to capture more demand may intensify competition, making it harder to maintain high fares and protect profits. Based in Atlanta, Delta now expects its annual fuel expenditure to increase by about $6 billion compared to last year—about $2 billion higher than its July forecast—due to the Iran war (link) causing global jet fuel prices to spike. Airlines worldwide are preparing for a prolonged fuel shock. Michael O’Leary, CEO of Ryanair Group RYA.I, said Thursday that high jet fuel prices could persist for another 12-18 months (link), adding more pressure on airlines to raise fares and control costs. https://www.reuters.com/graphics/AUTOMATED-20261008/A4A-JET-FUEL-DAILY-1Y/xmpjwjnmbvr/chart.png “In a high-cost environment, you can’t simply grow your way out,” Delta CEO Ed Bastian said on the earnings call. He noted that the industry has already taken steps to restrict capacity, but more measures will be needed next year to improve profitability. Bastian said Delta raised ticket prices about 20% this year, and passenger resistance has been limited. He is confident that even if fuel costs eventually drop, the high fares can still be maintained. Delta lowered its adjusted annual earnings per share forecast from the July prediction of $6.50-$7.50 to $5.10-$5.60. According to LSEG data, the midpoint of the new range is below analysts’ average expectation of $5.46. Third-quarter adjusted earnings per share were $1.72, four cents below analysts’ average forecast. In midday trading, shares of Delta dropped 1.7%, United Airlines UAL.O fell 1.4%, and both American Airlines AAL.O and Southwest Airlines LUV.N were down about 1%. Delta partly shields itself from rising fuel costs by owning a refinery outside Philadelphia (link), which is expected to generate over $700 million in profits this year. Even with this buffer, the airline expects its fourth-quarter fuel price to rise from $3.61 per gallon in Q3 to $4.25 per gallon. Delta forecasts adjusted fourth-quarter earnings per share to be between $1.15-$1.65, with the $1.40 midpoint roughly matching analysts’ average expectation of $1.39. Fare increases Government data shows that in the first eight months of 2026, U.S. airlines spent $42.9 billion on fuel, an increase of $13.2 billion compared to the same period last year despite slightly reduced consumption. According to the U.S. Bureau of Labor Statistics, strong demand and limited seat growth pushed average U.S. airline ticket prices up by about 25% year-on-year between April and August. https://www.reuters.com/graphics/USA-AIRLINES/FUEL/lbpgdnbzwvq/chart.png Analysts at Melius Research said that despite surging fuel costs, Delta’s ability to raise fares helps keep second-half profits roughly stable. Still, they warn that the company’s profit margin has struggled to improve over the years. “It is critical for margin improvement to maintain or raise fares in 2027,” they wrote in their research report. With industry capacity growth expected to accelerate in Q4, this challenge will likely become even tougher. Deutsche Bank analysts expect the proportion of fuel costs recouped through revenue measures to fall in Q4 and predict full recovery won’t happen until early 2027. Bastian noted that low industry returns are another reason for limiting capacity growth. He said Delta will be cautious with its 2027 capacity plan until the fuel price outlook becomes clearer. He added that international routes may account for a larger share of Delta’s capacity expansion compared to domestic routes. Currently, Delta says its premium cabins and corporate travel business remain strong, and its economy cabin business is gradually improving. With Q4 ticket bookings already exceeding 60%, Delta expects revenue to increase about 20% year-on-year, despite limited capacity growth. Executives said early booking trends for Q1 2027 are also encouraging. (For the convenience of non-native English speakers, Reuters automatically translates its reports into several
AI and Quantum: Trump's $6 Billion Plan Could Also Impact Bitcoin
Wall Street giants to release financial reports next week: stock trading revenue expected to approach $19 billion, "everyone is a winner" may be a thing of the past
According to analyst expectations compiled by Bloomberg, the combined equity trading revenue of the five major U.S. banks in the third quarter will approach $19 billion, but fixed income trading revenue is expected to drop to its lowest point of the year, and M&A activity has also cooled. Meanwhile, AI-driven cash optimization tools may lead to deposit outflows, sparking concerns about bank stocks in the market. Analysts believe that while the profit performance of each bank may further diverge, market concerns about the impact of AI may be overblown.
Crypto prices
More


