
Oracle Q3 Earnings Preview: Limited Performance Boost, Market Seeks Long-Term Optimistic Outlook
 Bitget2026/03/09 08:28
1.Investment Highlights Overview
Oracle will release its FY2026 third-quarter earnings after the US market close on March 10, with market consensus expecting revenue of about $16.9 billion (+20% YoY) and adjusted EPS of around $1.70-1.71 (+15% YoY). Investors are focusing on the speed of converting orders into revenue and the long-term return potential from high capital expenditures, which will directly impact stock volatility and trading opportunities. Driven by AI demand, the market anticipates the company to demonstrate a sustainable growth path rather than short-term performance fluctuations.
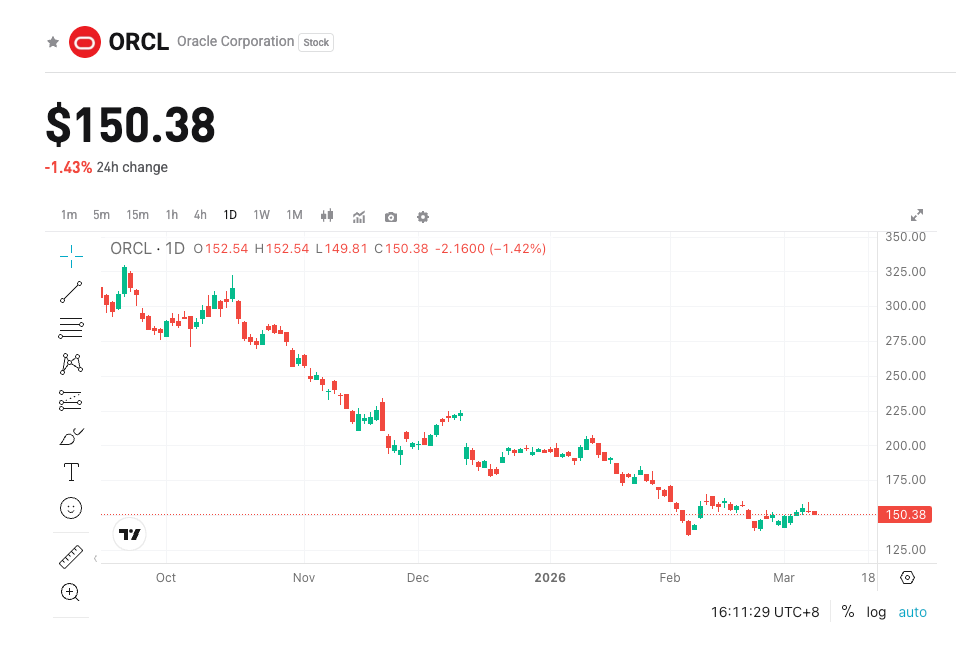
Bitget now supports ORCLUSD with 20x leverage contract trading—head over to seize volatility opportunities.
Current Bitget limited-time promotion: "Stock Newbie Gift, Zero-Fee Trading with 10 USDT"—trade more efficiently and cost-effectively!
2. Three Key Focus Areas Focus
1: Cloud Infrastructure Business Momentum
Cloud operations serve as Oracle's core growth driver, and their performance will shape market confidence in the company's AI positioning. Strong growth could uplift investor sentiment and drive short-term stock rebounds. Last quarter, total cloud revenue reached $8.0 billion (+34% YoY), with Oracle Cloud Infrastructure (OCI) at $4.08 billion (+68% YoY). If Q3 OCI growth exceeds expectations, it may signal robust demand and expand upside potential for the stock; conversely, a slowdown could intensify valuation pressures.
Focus 2: Remaining Performance Obligation Conversion Efficiency
RPO indicates future revenue potential, but conversion speed directly affects cash flow and earnings visibility, making it crucial for traders assessing long-term value. Last quarter, total RPO was $523 billion, with the next 12-month portion up +40% YoY. Accelerated conversion would show effective capacity expansion and help stabilize the stock; delays could raise doubts about execution and heighten volatility risks.
Focus 3: Capital Expenditure and Financing Balance
High Capex supports AI expansion but must align with cash flows to avoid diluting shareholder value and shifting the valuation framework. Over the past 12 months, operating cash flow was $22.3 billion, with Capex at $35.48 billion, resulting in negative free cash flow of $13.2 billion; FY2026 first-half Capex was $20.5 billion, with full-year expected to rise further. The company plans to raise $45-50 billion (half equity-related, half debt) to support client needs. If guidance shows a shortened return cycle, it will boost bullish confidence; otherwise, increased debt could continue to weigh on the stock.
3. Risks and Opportunities Coexist Upside Catalysts
- OCI and RPO metrics significantly beat expectations, indicating accelerated AI demand conversion and potentially sparking a stock surge.
- Management provides a clear Capex return timeline, strengthening the long-term growth narrative and attracting value investors.
- Contributions from clients (e.g., AMD, Meta, NVIDIA) translate into visible revenue, proving investment efficiency.
Downside Risks:
- Ongoing Capex overruns intensify cash flow pressures, dilute EPS, and spark financing concerns.
- Delayed order conversions expose supply bottlenecks, prompting the market to revise growth expectations downward.
- One-time items (e.g., last quarter's $2.7 billion pre-tax gain from Ampere stake sale) distort profit comparisons, reducing guidance credibility.
4. Trading Strategy Suggestions Bullish Logic
If OCI growth and RPO conversion surpass consensus, paired with positive capacity guidance, the company could regain favor in the AI theme, driving an upward stock breakout. Bearish Risks: If Capex return cycles extend or financing details fall short, the valuation shifts to a heavy-asset model, potentially leading to pullbacks, especially in rate-sensitive environments. Key Data Points:
- Cloud revenue and OCI sub-items (watch for growth above +34% YoY).
- Total RPO and next 12-month portion (+40% YoY as benchmark).
- Capex guidance and free cash flow (avoid expanding negatives).
- Adjusted EPS (evaluate after stripping one-time effects).
Operational Suggestions: In the short term, Oracle's turnaround via earnings alone is unlikely; the market craves a long-term optimistic vision. For retail investors, focus on the earnings call, prioritizing management's comments on client payments, return cycles, and guidance to build long/short positions.
Bitget now supports ORCLUSD with 20x leverage contract trading—head over to seize volatility opportunities! Current Bitget limited-time promotion: "Stock Newbie Gift, Zero-Fee Trading with 10 USDT"—trade more efficiently and cost-effectively!
Disclaimer: The above content is for reference only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Federal Reserve meeting minutes: All 19 policymakers support a rate hike in September, but reasons vary; most expect further hikes this year, suggesting no urgency in October.
Most officials view a September interest rate hike as an "insurance" measure against stubborn inflation; a minority see it as a necessary step to curb inflation. Overall, there is no indication of a desire to push for consecutive rate hikes. The "New Fed News Agency" emphasized the minutes: "Most participants believe that it may be appropriate to raise interest rates again before the end of the year." Nearly all officials believe inflation remains elevated and the labor market is close to full employment. Many noted that, despite the rise in long-term U.S. Treasury yields, financial conditions are still conducive to economic growth. Some officials believe that AI will boost investment and productivity, but may also contribute to inflation. The minutes revealed that the U.S.-Japan joint intervention in July to support the yen was a U.S. Treasury action, with no Federal Reserve funds used.
Solana Consolidates After Sharp Expansion
FLOKI Recovery Tests Key Resistance
100 Million Barrels Shrinkage? Reports Say EU Believes Oil Reserve Release Plan Mainly Fulfills Previous Commitments, Not New Quotas
Last Friday, G7 member countries agreed to release up to 100 million barrels of crude oil and diesel reserves. The IEA had announced a plan to release 400 million barrels in March, and as of last Friday, about 75 million barrels had yet to be released. Most EU member states believe that this action is simply fulfilling previous commitments rather than adding new releases. Regarding the earlier-than-scheduled release of diesel stocks emphasized in last week's G7 agreement, EU member states consider it feasible, but on a limited scale.
Crypto prices
More


