
What Fueled KEY's NII Expansion in 2025 Despite Easing Rates

KeyCorp’s KEY net interest income (NII) (on a tax-equivalent or TE basis) increased 23% year over year to $4.67 billion in 2025. The growth was fueled by strong commercial loan expansion, improved deposit trends, lower funding costs and continued balance sheet optimization efforts. This was achieved despite the Federal Reserve’s rate cuts during the year.
Similar to KEY, its regional peers, PNC Financial Services Group PNC and Huntington Bancshares Incorporated HBAN ended 2025 on a solid note. PNC reported a 6.6% year-over-year increase in NII (TE basis) to $14.5 billion, supported by lower funding costs, steady loan growth, and the continued benefit of fixed-rate asset repricing. HBAN’s NII (TE) rose 12% to $6 billion, driven by strong organic loan growth, contribution from the Veritex acquisition and net interest margin (NIM) expansion.
What Drove KeyCorp’s NII Growth in 2025
KeyCorp’s NII (TE) witnessed a compound annual growth rate (CAGR) of 2.8% over the last five years (2020-2025). Despite historically high interest rates, the metric declined in 2023 and 2024 due to a significant increase in deposit costs, while it rebounded strongly in 2025.
Likewise, PNC Financial and Huntington Bancshares reported decent NII growth. PNC recorded a six-year CAGR of 6.3% (ended 2025), while HBAN delivered a robust five-year (2020–2025) CAGR of 13.2%.
Coming back to KeyCorp, its commercial and industrial (C&I) loan portfolio grew 9% in 2025, while the bank intentionally reduced lower-yielding consumer loans. This strategic remix enhanced asset yields and supported NII growth. Simultaneously, strong commercial deposit growth and disciplined pricing enhanced the funding mix, lowered overall funding costs, and expanded NIM, further boosting NII.
KEY’s effective balance sheet repositioning, lower funding costs, solid C&I loan growth, a shift toward higher-yielding commercial loans, along with strong commercial deposit growth and disciplined deposit pricing, collectively supported NII in 2025.
KEY’s NII Outlook for 2026
KeyCorp expects NII (TE) to increase 8-10%, with fourth-quarter NII projected to reach approximately $1.3 billion. This will be supported by anticipated NIM expansion to a 3.00-3.05% by the fourth quarter, based on approximately $170 billion of average earning assets. In addition, average loan growth of 1–2%, along with deposit betas maintained in the low-to-mid-50% range, is expected to further support NII growth.
KEY shares have surged 23.5% in the past three months, compared with the industry’s growth of 19.5%.
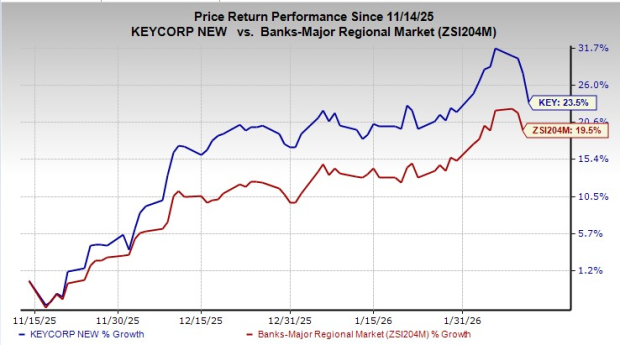
Image Source: Zacks Investment Research
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Micron (MU.US) Q4 earnings call: Management declares "No sign of supply-demand balance," 75% of shipments for next year already locked in; 2028 expected to be tighter than 2027
Micron Technology (MU.US) management expressed optimism during the Q4 earnings call, stating that AI-driven memory demand remains strong and that supply and demand will remain tight in 2027 and 2028.
After experiencing Muse, I cleared out my Airbnb holdings
A senior analyst heavily invested in Airbnb decided to sell all his Airbnb holdings just 10 days after experiencing Meta AI's Muse app. He believes that Muse not only understands his preferences but also helps him bypass Airbnb to book accommodations directly, at 60% lower prices. As AI agents begin to compare prices, cancel, and rebook on your behalf, the "traffic moat" that internet platforms depend on is under threat, and the era of "proactive e-commerce" may be dawning.
Goldman Sachs: AI Must Endure Hardship Before Rewards
Euro weakens below 1.1350 on higher US Treasury yields, Lagarde's dovish tilt
Crypto prices
More


