
Penske Q4 Earnings Miss Expectations, Dividend Raised

Penske Automotive Group PAG reported fourth-quarter 2025 adjusted earnings of $2.91 per share, which decreased 17.8% year over year and missed the Zacks Consensus Estimate of $3.19. The company registered net sales of $7.77 billion, which beat the Zacks Consensus Estimate of $7.64 billion. The top line also rose 0.6% from the year-ago quarter's level.
Penske’s gross profit in the reported quarter fell 5.3% on a year-over-year basis to $1.24 billion. The operating income decreased 20.8% to $275 million. Foreign currency exchange positively impacted revenues by $113.3 million, net income by $700,000 and earnings per share (EPS) by 1 cent.
In the reported quarter, same-store retail units declined 6.2% year over year to 115,898. Within the Retail Automotive segment, same-store new-vehicle revenues were down 9.6% to $3.18 billion. Same-store used vehicle revenues increased 2.8% to $2.10 billion.
Penske Automotive Group, Inc. Price, Consensus and EPS Surprise
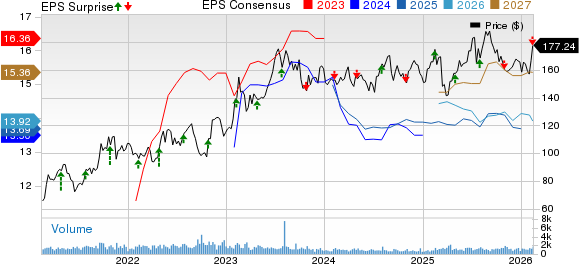
Penske Automotive Group, Inc. price-consensus-eps-surprise-chart | Penske Automotive Group, Inc. Quote
Segmental Performance of PAG
In the reported period, revenues in the Retail Automotive segment totaled $6.74 billion, which declined 4.8% from the year-ago quarter's level and topped our estimate of $6.73 billion. Total new and used vehicle deliveries were down 9.5% year over year to 105,478 units. Gross profit was $1.07 billion, down 5.7% year over year. The figure missed our estimate of $1.11 billion.
Revenues in the Retail Commercial Truck segment decreased 6.2% to $725.4 million and beat our estimate of $652.4 million. Gross profit in the segment was $121.4 million, down from $138.1 million reported in the year-earlier quarter. The figure beat our estimate of $106.1 million.
The Commercial Vehicle Distribution and Other segment’s revenues increased 35.3% to $303.3 million and beat our estimate of $257.4 million. Gross profit was $57.4 million, which increased from $45.8 million reported in the year-ago period and beat our estimate of $44.7 million.
Financial Tidbits
In the quarter under review, SG&A costs remained flat year over year at $924 million. As of Dec. 31, 2025, Penske had cash and cash equivalents of $64.7 million, down from $83.6 million as of Dec. 31, 2024. The long-term debt amounted to $1.81 billion, up from $1.13 billion as of Dec. 31, 2024.
In 2025, PAG repurchased 1,178,411 shares of common stock. As of Dec. 31, 2025, $247.5 million of stock repurchase authorization remained outstanding. As of Dec. 31, 2025, PAG had around $1.6 billion in liquidity.
Penske hiked its quarterly dividend by 2 cents to $1.40 per share, marking its 21st straight quarterly increase. The dividend will be paid on March 5, 2026, to its shareholders on record as of Feb. 25, 2026.
Penske Zacks Rank & Key Picks
PAG carries a Zacks Rank #3 (Hold) at present.
Some better-ranked stocks in the auto space are Modine Manufacturing MOD, Michelin MGDDY and Strattec Security STRT, each sporting a Zacks Rank #1 (Strong Buy) at present.
The Zacks Consensus Estimate for MOD’s fiscal 2026 sales and earnings implies year-over-year growth of 21.2% and 18.8%, respectively. The EPS estimate for fiscal 2026 and 2027 has improved 18 cents and 72 cents, respectively, in the past seven days.
The Zacks Consensus Estimate for MGDDY’s 2026 sales implies year-over-year growth of 6%. EPS estimate for 2026 and 2027 has improved 6 cents and 10 cents, respectively, in the past seven days.
The Zacks Consensus Estimate for STRT’s fiscal 2026 sales and earnings implies year-over-year growth of 2.1% and 16.2%, respectively. The EPS estimate for 2026 and 2027 has improved 85 cents and 48 cents, respectively, in the past seven days.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Swiss Franc reaches fresh 16-month lows ahead of CPI data
Arthur Hayes forecasts $1 million Bitcoin by 2030, links target to AI debt risks
AI valuation divergence intensifies! Anthropic IPO: Enthusiastic Silicon Valley bids $2 trillion, while a cautious Wall Street only recognizes $1.5 trillion
The valuation debate surrounding Anthropic’s IPO is exposing a pricing gap between Silicon Valley and Wall Street. Silicon Valley venture capitalists are still betting heavily on AI growth at high valuations, with some investment banks discussing an early valuation of around $2 trillion. Meanwhile, Wall Street public market institutions are focusing on high interest rates, capital expenditure on computing power, and ongoing financing pressures, and are leaning toward a $1.5 trillion valuation.
Micron (MU.US) Q4 earnings call: Management declares "No sign of supply-demand balance," 75% of shipments for next year already locked in; 2028 expected to be tighter than 2027
Micron Technology (MU.US) management expressed optimism during the Q4 earnings call, stating that AI-driven memory demand remains strong and that supply and demand will remain tight in 2027 and 2028.
Crypto prices
More


